

Key Takeaways
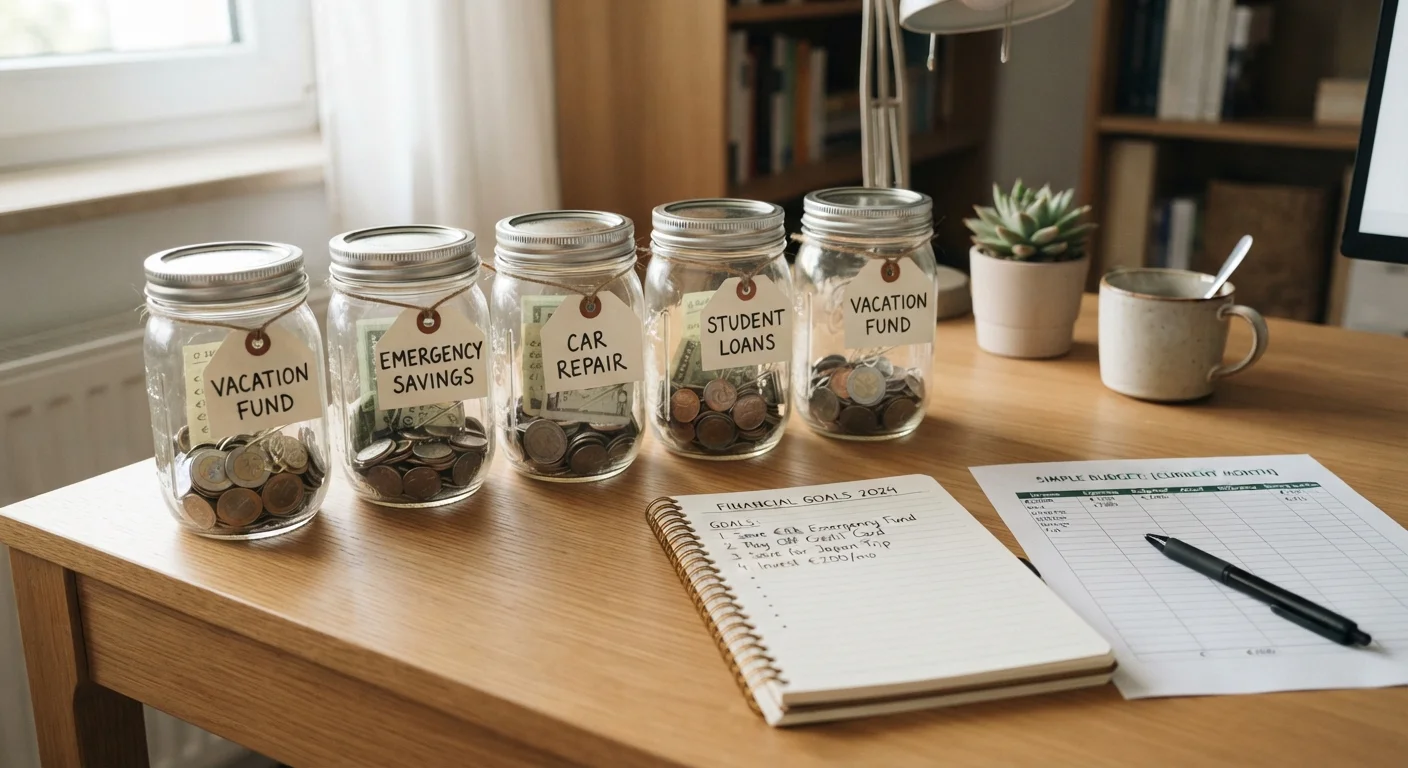
- Assigning each goal a separate account or named bucket prevents funds from blending together.
- Prioritizing goals by urgency and timeline tells you how much to direct where each month.
- Automating transfers removes the decision point and reduces the chance of skipping a contribution.
- Reviewing allocations every few months keeps the plan matched to your actual income and goals.
- An emergency fund should be funded before or alongside other goals, not after them.
What you will need
Why saving for multiple goals at once is harder than it looks
Most savings advice focuses on a single goal: pay off debt, build an emergency fund, save for retirement. Real financial life rarely works that way. Most adults are working toward several targets at once, and without a system, the money tends to blur together or drift toward whichever goal feels most urgent on any given day.
The two most common failure modes are keeping all savings in one account (where balances blend and goals become invisible) and funding goals sequentially (where lower-priority goals never get started because higher ones take years to finish). A structured parallel approach avoids both problems.
This article is general financial information and not personalized advice. For decisions specific to your situation, consult a licensed financial professional.
What you will need
How to build and maintain the system
The steps below walk through a repeatable process for setting up parallel savings across multiple goals. The core idea is simple: give each goal its own account, automate contributions, and check in regularly. The details are what make it stick.
List every goal and assign a target amount and date
Write down each goal you are working toward. For each one, record a specific dollar target and the date by which you want to reach it. "Save for vacation" is too vague. "Save $3,000 by next August" gives you a number to work backward from.
With a target and a date, you can calculate a monthly contribution: divide the remaining amount needed by the number of months left. This turns each goal into a concrete monthly line item rather than a vague intention.
Rank goals by urgency and importance
Not all goals can receive equal funding at once. Sort your list by two factors: how soon you need the money, and what happens if you do not have it. An emergency fund sits at the top of most lists because the cost of not having one can ripple through every other goal. A down payment for a home purchase three years out ranks differently than a car repair fund you may need within months.
This ranking tells you where to direct extra dollars when your budget is tight and which goals to build first. See how to size an emergency fund before finalizing your priority order.
Open a separate account for each goal
Keeping all savings in one account makes it easy to accidentally spend money earmarked for something specific. Opening separate accounts, or using named sub-accounts if your bank offers them, gives each goal its own balance. When you check your accounts, you see exactly where each goal stands.
Many banks allow multiple savings accounts with no additional fee. If yours does not, look for institutions that offer sub-account or savings bucket features. The savings buckets approach covers this structure in detail.
Set up automatic transfers on payday
Manual transfers depend on you remembering and choosing to act every pay period. Automation removes that friction. Schedule a transfer to each goal account to run the day your paycheck lands, or the day after, before you have a chance to spend the money elsewhere.
Start with amounts based on your priority ranking and monthly calculation from Step 1. If your budget is tight, even small automated amounts keep momentum. A goal receiving $50 per month moves forward. A goal receiving nothing stalls.
Review and adjust allocations every three months
Income changes, goals get reached, and new priorities appear. A set-it-and-forget-it approach works for the transfers themselves, but the allocation amounts need a periodic check. Every quarter, look at each goal's balance and compare it to where it should be at that point on your timeline.
If a goal is ahead of schedule, you can temporarily shift some of its monthly contribution to a goal that is behind. If your income has increased, add the extra to your highest-priority unfinished goal first before spreading it across others. For guidance on handling a bonus or tax refund, see how windfalls fit into a savings plan.
Close or redirect accounts when a goal is complete
When you reach a goal, close or rename that account promptly. Leaving a funded account open with no clear purpose makes it a target for unplanned spending. Redirect the monthly contribution that was going to the completed goal to the next priority on your list. This compounds your progress: each finished goal frees up cash flow for the ones still in progress.
Fund your emergency reserve first
Before directing significant amounts to discretionary goals like travel or home upgrades, build at least a partial emergency reserve. Without it, one unexpected expense can force you to raid your other goal accounts and reset months of progress. A common starting target is one month of essential expenses; build from there while funding other goals in parallel.
If you share finances with a partner or household member, the allocation decisions become a joint exercise. The shared finances framework covers how to structure that conversation without requiring every dollar to be pooled.
For a broader look at whether separating goals into accounts is right for you, weigh the pros and cons of one savings account versus multiple before you decide on your structure.
Variable income requires a different approach
If your paycheck changes month to month, fixed automatic transfers can cause overdrafts. Consider setting transfers as a percentage of each deposit rather than a fixed dollar amount. The saving on variable income article covers strategies suited to irregular earnings.
Once your system is running, the account type you use for each goal matters. Short-term goals need accessible funds. Longer-term goals can sit in accounts that earn more. comparing CDs and high-yield savings accounts helps match account types to timelines.
This article is for general informational purposes only and does not constitute personalized financial, investment, or tax advice. Consult a qualified financial professional before making decisions about your own savings or finances.