

Key Takeaways
- Consistency in saving, not the size of each deposit, is what compounds into meaningful progress over time.
- Different savings goals belong in different account types, matched to how soon you will need the money.
- Automating transfers removes the decision of whether to save, making the habit nearly effortless.
- Organizing savings into named, purpose-driven buckets reduces the temptation to raid one goal for another.
- A periodic review catches drift early and keeps your savings aligned with changing priorities.
Why consistent saving matters more than the amount
Most adults know they should save. Far fewer have a reliable system for doing it. The gap between knowing and doing usually comes down to one misconception: that saving only counts when the amount is large. In practice, frequency and consistency do more work than any single large deposit.
When saving happens on a schedule, it becomes a background function of your finances rather than a conscious sacrifice. Money set aside before it reaches your checking account is money you adjust around without noticing. That behavioral adjustment is the foundation everything else builds on.
Savings also serve different purposes at the same time: a cushion for the unexpected, a fund for planned purchases, and a resource for long-term goals. Because those purposes have different timelines and different emotional weights, treating them as one undifferentiated pile makes it harder to protect any of them.
This guide covers the full picture: where to keep savings, how to match accounts to goals, and how to build a routine that holds up when life gets complicated. For a broader financial foundation, this complete guide to personal budgeting covers the spending side of the equation in equal depth.
This article is general financial education, not personalized financial advice. For decisions specific to your situation, consult a licensed financial professional.
Types of savings accounts and how they work
The account type you choose should match the timeline and purpose of the money inside it. Using the wrong account can mean earning less interest, paying unnecessary fees, or facing penalties when you need the funds.
Deposit accounts for short-term and emergency funds
Standard savings accounts at banks or credit unions are insured by the FDIC or NCUA up to applicable limits, meaning your principal is protected. High-yield savings accounts operate the same way but carry higher interest rates, typically available at online banks. For money you may need within a year, these accounts balance access with modest growth.
Money market accounts are a variation: they often come with check-writing or debit access and may require a higher minimum balance. The interest rate generally falls between a standard and high-yield account.
Certificates of deposit for money with a fixed timeline
A certificate of deposit (CD) locks in a fixed interest rate for a set term, ranging from a few months to several years. In exchange for that lock-in, the rate is usually higher than a standard savings account. Early withdrawal typically triggers a penalty, so CDs work best when you are confident you will not need the funds before the term ends.
Tax-advantaged accounts for long-term goals
Retirement-oriented accounts such as IRAs and employer-sponsored 401(k) plans hold savings that grow with certain tax advantages. These are not designed for near-term access; early withdrawal usually triggers taxes and penalties. Health Savings Accounts (HSAs), available to those enrolled in qualifying high-deductible health plans, offer a separate tax advantage specifically for medical expenses.
Match your account to your timeline
Before opening any savings account, note when you expect to need the money. For funds you might need within months, prioritize liquidity and FDIC or NCUA insurance. For money earmarked for years out, you can consider options with higher yields in exchange for less immediate access. Mismatching these can cost you either in penalties or in foregone interest.
Setting goals that match your real life
Vague intentions produce vague results. A goal defined by a specific amount and a target date is one you can plan toward and measure. The three categories below cover most of what adults save for.
Emergency fund
An emergency fund is cash reserved for unplanned expenses: a car repair, a medical bill, a gap in income. A common guideline is three to six months of essential expenses, held in a liquid account you can access without delay. The right amount depends on your job security, fixed obligations, and household situation. For most people, building this fund before other goals is the logical starting point.
Short- and medium-term goals
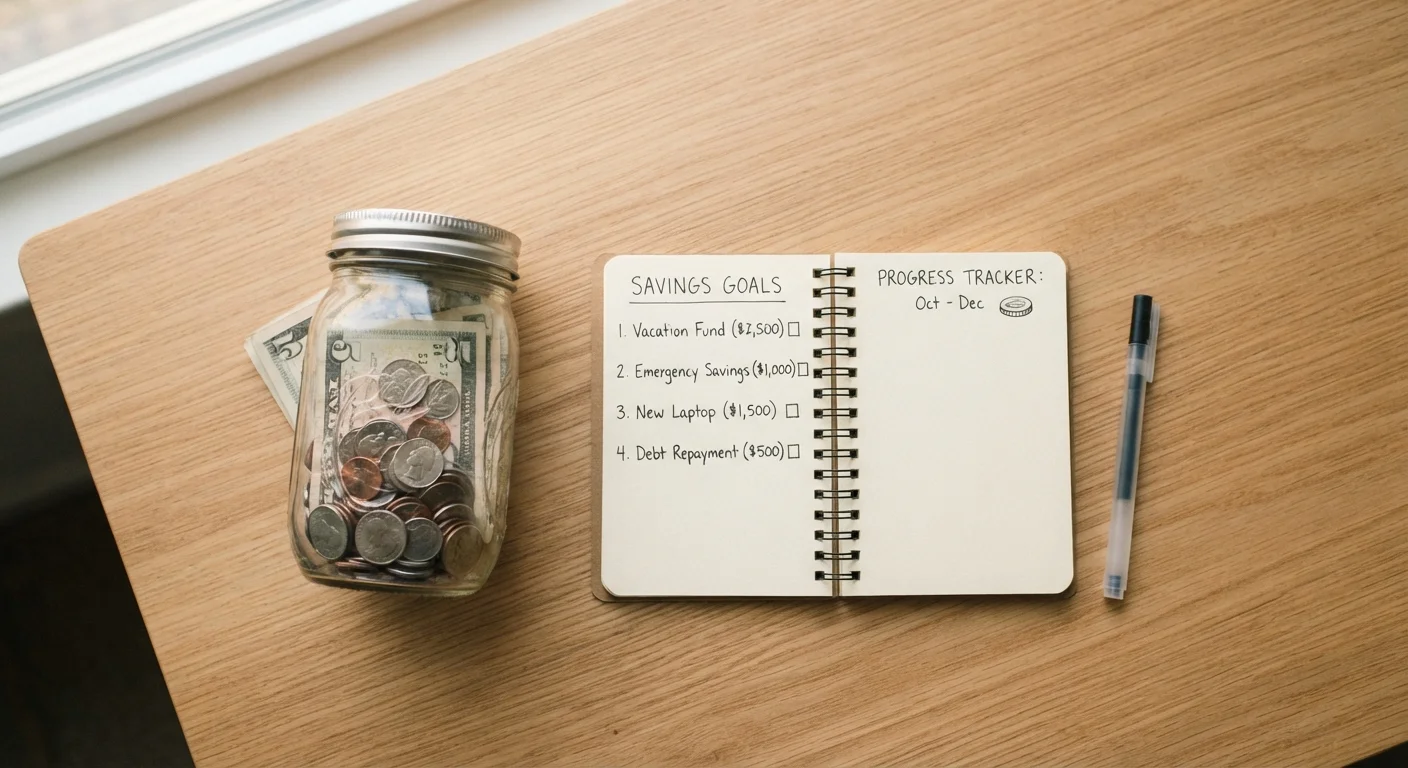
These are purchases or events with a known or estimated cost and a timeline shorter than a decade: a home down payment, a vehicle, a wedding, a relocation, continuing education. Each goal deserves its own savings target so you can see exactly where you stand. Organizing savings by named buckets is one practical method for keeping these goals from blurring together.
Long-term and life-stage goals
Goals further out, such as retirement or funding a child's education, involve longer compounding periods and different account structures. Financial needs shift significantly across adult life stages, and the savings strategies that fit a person in their twenties differ from those appropriate in their forties or fifties.
Building a savings routine that sticks
A routine removes friction. When saving depends on a conscious monthly decision, it competes with every other spending pressure. When it is automatic, it does not.
Automate transfers
Most banks allow scheduled transfers from a checking account to a savings account on a fixed date. Setting this to coincide with payday means savings move before discretionary spending can absorb them. Even a small fixed amount, transferred every pay period, accumulates steadily.
Treat savings as a fixed expense
Budgeting frameworks that allocate income to savings first, before discretionary categories, tend to produce better outcomes than those that save whatever is left over. Core budgeting strategies can help you find the allocation that fits your income and obligations.
Match the account to the goal's timeline
Short-term goals belong in liquid, accessible accounts. Locking money needed within six months into a multi-year CD creates a mismatch that can cost you in penalties. Longer-term goals can tolerate less liquidity in exchange for better returns.
When setting up automatic transfers, use a separate savings account at a different institution from your primary checking. The extra step required to move money back acts as a natural spending brake.
Behavioral finance research consistently shows that friction reduces impulse spending, and account separation is one of the simplest structural ways to create it.
Name each savings goal in your account or app, not just in a spreadsheet. Seeing 'vacation fund' or 'car repair buffer' instead of a generic account number makes the purpose concrete and reduces the temptation to redirect the money.
Goal labeling increases goal adherence by making the intended use of money psychologically salient at the moment a spending decision arises.
Tracking progress and adjusting over time
A savings plan set up once and never reviewed will drift. Income changes, goals shift, and costs turn out different from estimates. Periodic check-ins catch those gaps early.
At minimum, a quarterly review should cover: whether automated transfers are still running, whether each goal is on pace, and whether any new priorities have emerged. A structured savings checkup gives you a repeatable framework for this rather than starting from scratch each time.
When circumstances change significantly, such as a job change, a new household member, or a major purchase, a fuller reassessment makes sense. The goal is not to hold rigidly to an old plan but to keep your savings working toward what actually matters to you now.
Progress is also worth acknowledging concretely. Watching a balance approach its target is information you can act on: it tells you when to open the next goal bucket, when to increase a transfer amount, and when a goal is funded and can be closed. Concrete milestones make the abstract habit of saving feel like it is going somewhere specific.