

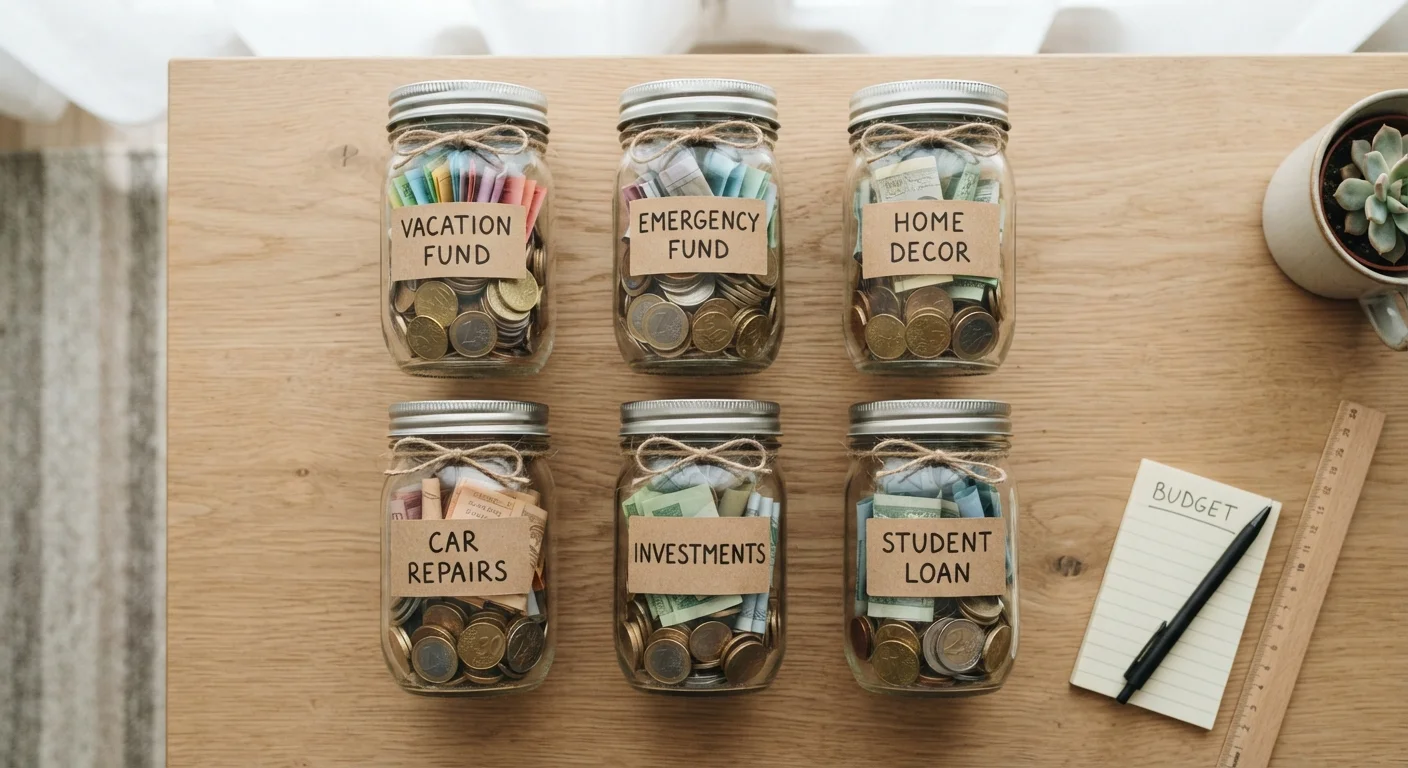
Key Takeaways
- Naming each savings bucket after a specific goal reduces the urge to raid that money for other purposes.
- You do not need a separate bank account for every bucket; a clear tracking system works too.
- Start with three to four buckets, then expand as your priorities become clearer.
- Automating transfers into each bucket on payday removes the decision from your hands each month.
- Regularly reviewing bucket balances keeps contributions aligned with shifting life priorities.
What you will need
Why buckets work better than one lump sum
When all savings sit in a single account, the balance looks like one undifferentiated resource. That makes it easy to justify a purchase by telling yourself you'll make up the difference later. Labeled buckets break that pattern by tying each dollar to something specific: a home repair, a vacation, a down payment.
The case for keeping all savings in one account is straightforward simplicity, but that simplicity has a cost. Without separation, it's harder to tell at a glance whether you're on track for any individual goal. Buckets give you that visibility.
This approach also connects naturally to pay-yourself-first budgeting, where you fund savings immediately on payday before discretionary spending gets a chance to absorb the money. Buckets give the pay-yourself-first method its destinations.
Naming buckets changes behavior
Research in behavioral economics consistently shows that labeling money for a specific purpose makes people less likely to spend it on something else. A bucket called 'car repair fund' feels different from an unnamed balance, even if the dollar amount is identical. Give each bucket a name that matches the real goal, not a generic category.
How to set up your savings bucket system
What you will need
Spreadsheet or budgeting app
Track each bucket's target amount, current balance, and monthly contribution in one place.
Separate savings sub-accounts
Some banks allow multiple labeled sub-accounts under one login, which physically separates each bucket.
Automatic transfer setup
Schedules recurring deposits into each bucket on payday without manual action.
List every goal you want to save toward
Write down all the financial goals currently on your mind. Include both near-term goals (a car repair fund, a holiday trip) and longer-range ones (a home down payment, a career transition cushion). Do not filter yet. The point here is to see everything in one place so you can make deliberate choices about what gets a bucket.
Savings milestones at different life stages can help you spot goals you may not have considered.
Assign a priority and a target amount to each goal
Sort your list into three groups: goals you need to fund in the next 12 months, goals on a one-to-five-year horizon, and longer-term goals. Then assign a target dollar amount to each. For irregular future expenses, sinking funds follow the same logic: divide the total by the number of months until you need it to find your monthly contribution.
Home-related costs in particular deserve their own bucket. Maintenance and repairs have a way of arriving without warning, as outlined in budget categories that catch people off guard.
Decide how many buckets to open and where to hold them
You do not need a separate bank account for every goal. Options include:
- Sub-accounts within one savings account (many banks allow this with custom labels)
- A single account tracked in a spreadsheet with a column per bucket
- A budgeting app that supports goal-based categories
For goals with a timeline of more than a year, consider whether a high-yield savings account or certificate of deposit fits better than a standard account. Both carry tradeoffs in flexibility versus rate.
Set a monthly contribution for each bucket
Divide each target amount by the number of months until you need it. That figure is your monthly deposit for that bucket. Add up all the monthly contributions and compare the total to what you can realistically set aside after fixed expenses.
If the total exceeds what is available, go back to your priority ranking and reduce contributions to lower-priority buckets first. Understanding which expenses are fixed and which are flexible makes this comparison easier.
Automate transfers on payday
Set up automatic transfers from your checking account to each bucket to execute on or immediately after your regular payday. Automation removes the monthly decision and closes the window between receiving income and spending it before saving occurs. This is the operational backbone of pay-yourself-first budgeting.
If you share finances with a partner, a shared household budget framework can help you coordinate which buckets are joint and which are individual.
Too many buckets can stall progress
Splitting a modest income across eight or ten buckets often means each one grows so slowly that goals feel unreachable. If monthly contributions to any single bucket fall below about $10, consider whether that goal belongs in its own bucket now or should wait until another goal is funded.
Keep an emergency fund separate from all buckets
A savings bucket system organizes goals, but it does not replace a dedicated emergency fund. Emergency reserves should stay in a distinct account and carry a clear rule: they are only for genuine unexpected expenses such as job loss or an urgent medical bill. Mixing emergency funds with goal-based buckets creates confusion about what is truly available in a crisis. See what an emergency fund is and how to size it before you build out your bucket structure.
Maintaining and adjusting over time
A bucket system is not static. Life changes, and so do priorities. A periodic savings review every three to six months gives you a chance to increase contributions to buckets that matter more now, pause ones that no longer apply, and add new buckets for goals that have emerged.
When a windfall arrives, such as a tax refund or work bonus, the bucket structure makes it straightforward to allocate it intentionally. How windfalls fit into a savings plan covers the decision-making process in more detail. Rather than depositing the whole amount into one account and hoping it sticks, you can distribute it across whichever buckets are furthest from their targets.
If you are saving for multiple goals at the same time, the bucket model is one of the cleaner ways to avoid confusion about which money belongs where. The goal is clarity, not complexity. Keep the number of buckets manageable and adjust contributions as your income or priorities shift.
This article is for general informational and educational purposes only. It does not constitute personalized financial advice. For guidance specific to your situation, consult a qualified financial professional.