

Key Takeaways
- High-interest debt almost always costs more than savings earn, so paying it first generally makes mathematical sense.
- A small emergency fund built alongside debt repayment can prevent new debt from forming when unexpected costs arise.
- Employer retirement matches are effectively guaranteed returns and usually worth capturing even while carrying debt.
- Splitting available dollars between debt and savings is a valid strategy when it supports consistent financial habits.
- The right balance depends on interest rates, income stability, and your specific goals, not a one-size-fits-all rule.
Why this is rarely a binary choice
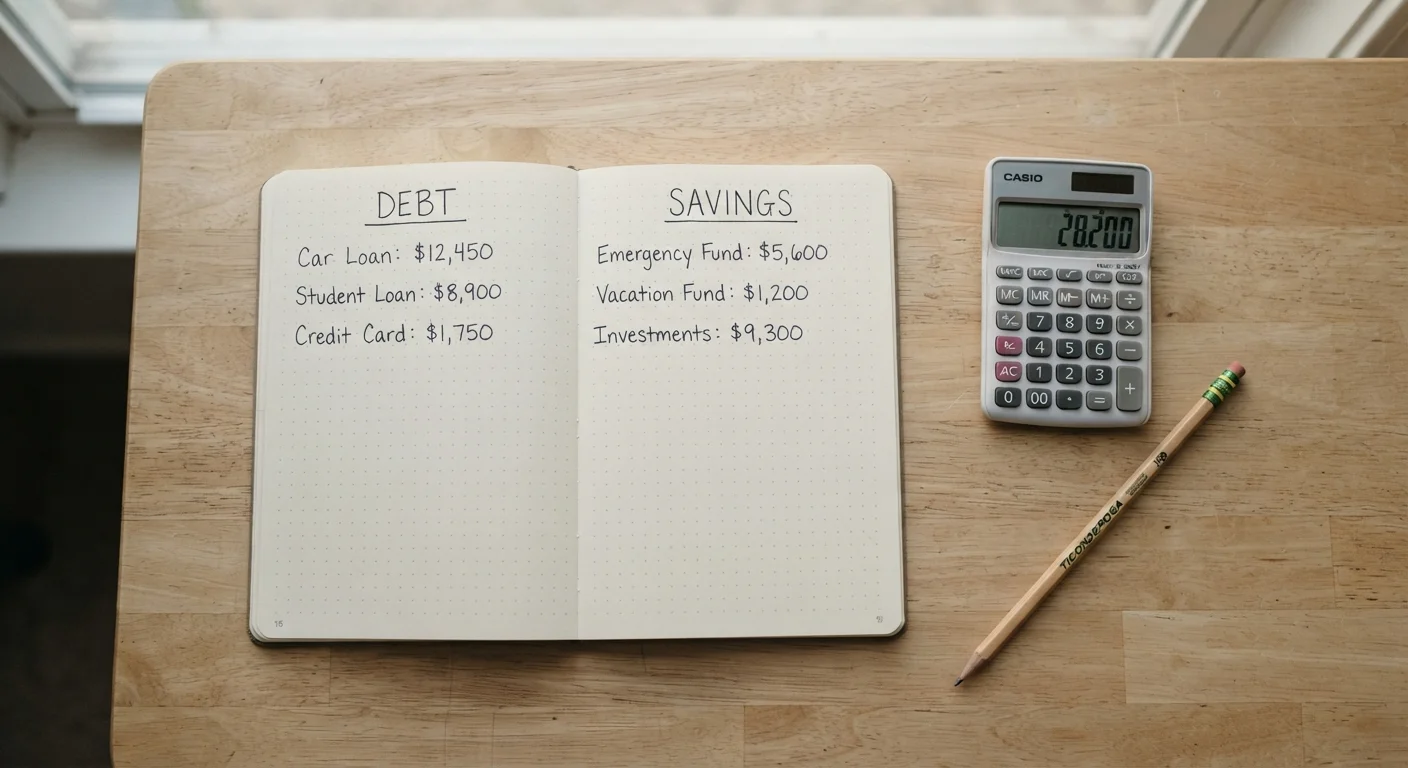
Most personal finance advice frames debt repayment and saving as competing priorities. In practice, they rarely are. A person who aggressively pays down a credit card balance but holds no cash reserves is one car repair away from putting that same expense back on the card. The math that favors rapid debt payoff can unravel quickly when an emergency has nowhere to go.
The better framing is a question of proportion: how much of each available dollar goes toward debt, and how much goes toward building financial cushion? That proportion shifts depending on the types of debt you carry, the interest rates attached to them, and what stage of life you are in. See the Budgeting Basics hub for context on building the foundation that makes this balancing act possible.
This article is for general informational purposes only and is not personalized financial advice. Consider consulting a licensed financial professional for guidance tailored to your situation.
How interest rates change the math
Interest rates are the clearest guide to prioritization. If a credit card charges 22% annually and a savings account yields 4.5%, every dollar sitting in savings rather than paying down that card costs money on net. The gap is what matters, not the absolute rate on either side.
Low-rate debt changes that calculus. A federal student loan at 5% or a mortgage at 6.5% may not demand the same urgency. Dollars redirected to savings or investments at comparable or higher expected returns can be a reasonable trade-off over a long time horizon, though investment returns are never guaranteed and carry risk.
22%+
Average credit card interest rate in the US
The Consumer Financial Protection Bureau has reported average credit card rates above 20% in recent years, illustrating the cost of carrying revolving balances.
~40%
Adults without enough savings to cover a $400 emergency
The Federal Reserve's Report on the Economic Well-Being of U.S. Households has repeatedly found that a significant share of adults would struggle to cover a small unexpected expense without borrowing.
For debt and credit decisions, a useful exercise is listing every debt with its interest rate, then comparing those rates against what your savings or investment accounts realistically earn. That comparison tells you where each marginal dollar does the most work.
The emergency fund question
Building a full three-to-six months of expenses before paying down debt is advice worth questioning when you carry high-interest balances. A smaller starter fund, often cited as $500 to $1,000, can absorb common shocks without requiring you to pause debt repayment indefinitely.
Once that buffer is in place, directing most available dollars toward high-rate debt while maintaining the buffer is a workable approach for many people. The buffer's job is to break the cycle where unexpected costs become new debt. Without it, the payoff progress resets.
Saving for multiple goals at once requires a system that keeps each purpose visible. Named accounts or savings categories can help prevent the emergency fund from being quietly spent on non-emergencies.
Best practices for managing both at once
Build a starter emergency fund before accelerating debt payoff
Without any cash reserve, an unplanned expense often becomes new debt at the same or higher interest rate than the debt being paid off. A modest buffer breaks that cycle and keeps payoff momentum intact.
Capture any available employer retirement match before doing anything else
An employer match is a defined, immediate return on the contributed dollar. Passing it up to pay down debt at a lower rate than the effective match return is rarely the optimal choice.
Rank debts by interest rate and direct extra payments to the highest-rate balance first
High-rate debt grows faster than low-rate debt and erodes more financial capacity over time. Targeting the most expensive balance reduces the total cost of carrying debt.
Automate both debt payments and savings contributions on payday
Manual transfers rely on willpower and available balance, both of which vary. Automation removes the decision point and ensures both goals receive funding before discretionary spending begins.
Reassess the debt-to-savings split whenever income or expenses change materially
A proportion that worked at one income level may leave too little buffer after a raise, a job change, or a large recurring expense. Regular reviews keep the allocation matched to current reality.
Whichever approach you use, consistency matters more than perfection. Missing a month of extra debt payments or temporarily pausing savings contributions is recoverable. Abandoning the system entirely, usually because it felt too rigid, is harder to undo.
The debt avalanche and debt snowball methods each offer a structured way to sequence payoffs once you have decided how much to allocate toward debt overall. For additional tactics, strategies to pay down debt faster covers options that can accelerate progress without requiring a large income increase.
Retirement contributions as a special case
Employer retirement matches occupy a different category from general savings. When an employer matches contributions up to a set percentage of salary, declining to contribute enough to capture that match is leaving compensation on the table. The match is an immediate, certain return that high-interest debt rarely exceeds on a dollar-for-dollar basis.
Contributing enough to get the full match while simultaneously paying down debt is a reasonable approach for many people in this situation. Beyond the match threshold, the decision of whether to increase retirement contributions or accelerate debt payoff depends on factors including your tax situation, debt interest rates, and how many years you have until retirement.
The pay-yourself-first budgeting framework addresses how to structure these automatic allocations so retirement and debt payments both happen before discretionary spending gets a chance to absorb the dollars.