

Key Takeaways
- Goal-based saving assigns money to specific purposes, which can reduce unplanned spending from savings.
- General saving builds one pool of funds that you can direct toward any need as it comes up.
- Many people use both: a general buffer for flexibility and separate goal accounts for larger targets.
- Neither approach guarantees financial outcomes; individual habits and income matter more than the method alone.
- Consulting a licensed financial adviser can help you structure a saving plan suited to your situation.
Option A
Goal-based saving
A structured approach that ties each saved dollar to a specific purpose.
Best for: People working toward defined milestones such as a home down payment, vacation, or emergency fund target.
Option B
General saving
A flexible approach that builds a single balance without designated purposes.
Best for: People who want a simple system and prefer to allocate money as needs arise.
If you have a clear target with a deadline, such as a home down payment or a trip
Goal-based saving
Separating funds for a named purpose makes the target concrete and reduces the chance you spend the money on something else before the deadline arrives.
If your income is irregular or your priorities shift frequently
General saving
One flexible pool lets you respond to what matters most without the friction of rebalancing multiple designated accounts.
If you want to handle day-to-day surprises while also working toward bigger milestones
Goal-based saving
Keeping a separate general buffer alongside named goal accounts gives you both stability and direction without those two purposes competing for the same dollars.
How each approach works
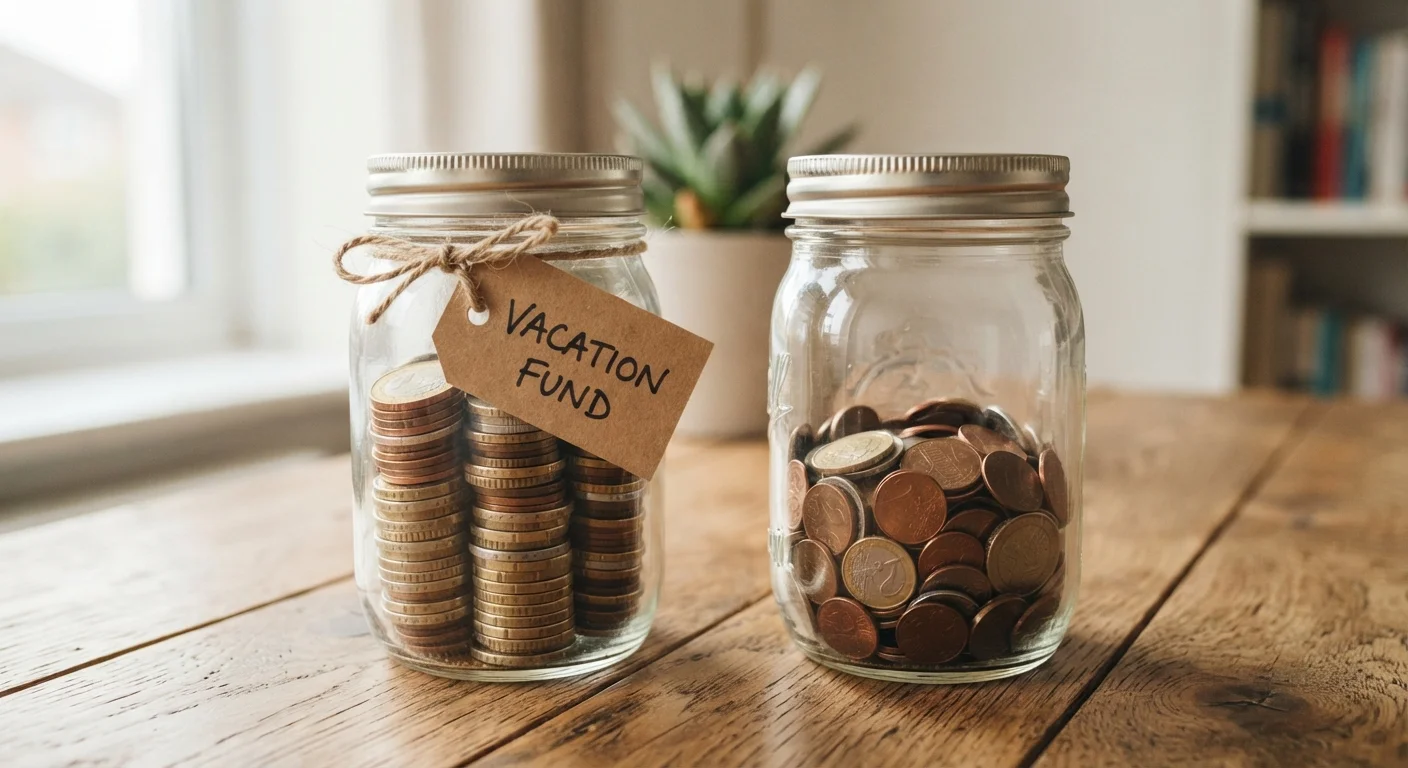
Goal-based saving means setting aside money for a named purpose: a car repair fund, a wedding, a six-month emergency reserve, a college account. Each goal gets its own target amount, often its own account or labeled bucket, and sometimes a timeline. Progress is measurable because you know exactly where you stand relative to a specific number.
General saving means depositing money into a balance without assigning it a job in advance. The funds accumulate and you decide how to use them when a need or opportunity appears. The system is simple to maintain and requires no ongoing tracking of multiple buckets.
Savings buckets are a common way to practice goal-based saving without opening a separate bank account for every purpose: you mentally (or digitally) divide one account into named portions.
Where goal-based saving has an edge
Goal-based saving and behavioral research
Behavioral economics research has documented what practitioners call "mental accounting," the tendency people have to treat money differently depending on its perceived purpose. While labeling savings does not change the actual dollars, it can change how readily someone spends them. This does not guarantee better outcomes, but it is one reason financial planning frameworks often encourage naming goals explicitly.
When money has a name, it is harder to spend casually. A balance labeled "home down payment" feels different to touch than a general savings account balance that looks like available cash. This psychological effect is one reason goal-based savers often report reaching large targets more consistently than they did with a single account.
Goal-based saving also makes trade-offs visible. If you want to add a new goal, you have to decide what gets less. That friction is useful: it forces a conversation with yourself about actual priorities rather than letting spending happen by default.
For anyone juggling several financial milestones at once, saving for multiple goals simultaneously is possible with the right allocation system.
Where general saving has an edge
General saving suits people whose financial picture changes often. If your income varies month to month, maintaining fixed contributions to several named goals can feel like a rigid system that breaks whenever something unexpected happens. One pool is easier to manage under those conditions.
A general balance also avoids the administrative overhead of multiple accounts or spreadsheet buckets. For someone who finds that complexity discouraging, a simpler system they actually use beats a sophisticated one they abandon.
Keeping all savings in one account has real trade-offs, but for some people the simplicity outweighs the organizational benefits of separation.
| Criterion | Goal-based saving | General saving |
|---|---|---|
| Structure | Multiple named purposes or buckets | Single undivided balance |
| Motivation | Concrete target reinforces progress | Flexibility reduces pressure |
| Trade-off visibility | High: new goals require reallocation | Low: money is fungible until spent |
| Best timeline | Defined deadlines or milestones | Open-ended or variable needs |
| Administrative effort | Higher: multiple accounts or labels | Lower: one account to track |
| Risk of casual spending | Lower when funds are labeled | Higher if no mental separation exists |
Choosing an account structure that fits
The approach you choose affects which account types make sense. Goal-based savers with fixed timelines sometimes use certificates of deposit for portions of their savings, since a locked rate aligns with a defined deadline. Those who need flexibility usually stay in accounts they can access without penalty. Certificates of deposit versus high-yield savings accounts covers how each fits different saving timelines.
Whatever structure you use, pairing it with a clear budget matters. Pay-yourself-first budgeting moves savings contributions to the top of the spending sequence, before discretionary spending, which works with either goal-based or general saving.
For a broader view of how accounts, goals, and habits connect, the complete picture of personal savings covers the full range of decisions involved in building a saving practice.
This article is for general informational purposes only and does not constitute personalized financial or investment advice. Consult a licensed financial adviser for guidance suited to your individual circumstances.